
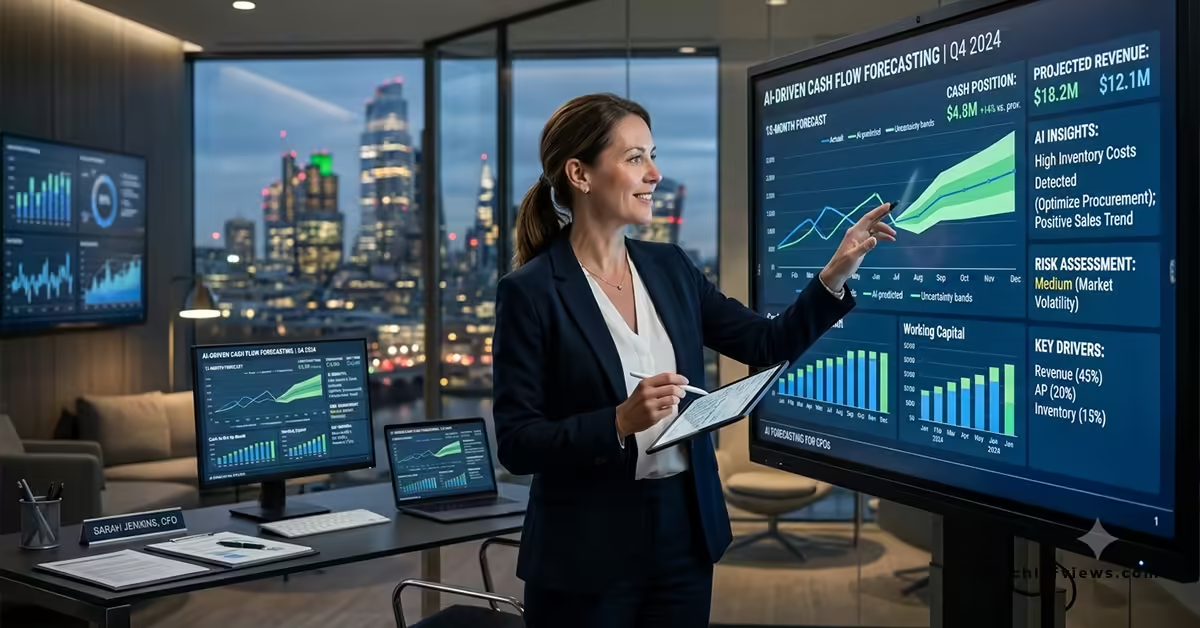
AI-driven cash flow forecasting for CFOs turns a weekly spreadsheet scramble into a living, decision-ready signal. Finance teams no longer wait for month-end surprises. They see liquidity gaps forming, test payment delays in real time, and reallocate capital before the balance sheet feels the hit.
Quick overview of what matters:
- It replaces static historical averages with machine-learning models that learn customer payment behavior, seasonality, and external signals.
- Accuracy jumps from the typical 60-70% range of manual methods toward 85-95% on short- and medium-term horizons when data is clean.
- The biggest operational win is earlier visibility into late payers and working-capital swings—exactly where most cash crunches start.
- This capability sits at the heart of broader CFO priorities for agility resilience and intelligence 2026, giving leaders the intelligence layer that supports faster decisions and stronger buffers.
Boards now expect the CFO to answer “how much cash will we have in six weeks?” with confidence, not caveats. AI delivers that answer when the foundations are right.
Why traditional cash forecasting falls short in 2026
Most treasury and FP&A teams still lean on spreadsheets or basic ERP roll-ups. Those tools excel at telling you what already happened. They struggle with the messy middle—customers who stretch terms, seasonal volume spikes, or a sudden supplier demand for earlier payment.
The Association for Financial Professionals’ 2026 Treasury Benchmarking Survey ranked cash and liquidity forecasting as the top challenge for nearly half of practitioners. Manual variance analysis asks why last week missed. AI-driven cash flow forecasting for CFOs asks where next week is already drifting and what to do about it.
That shift is material. When 46% of finance leaders in Deloitte’s Finance Trends 2026 survey flag working-capital optimization as a leading use case for agentic AI, the message is clear: the old process is no longer good enough.
How AI-driven cash flow forecasting actually works
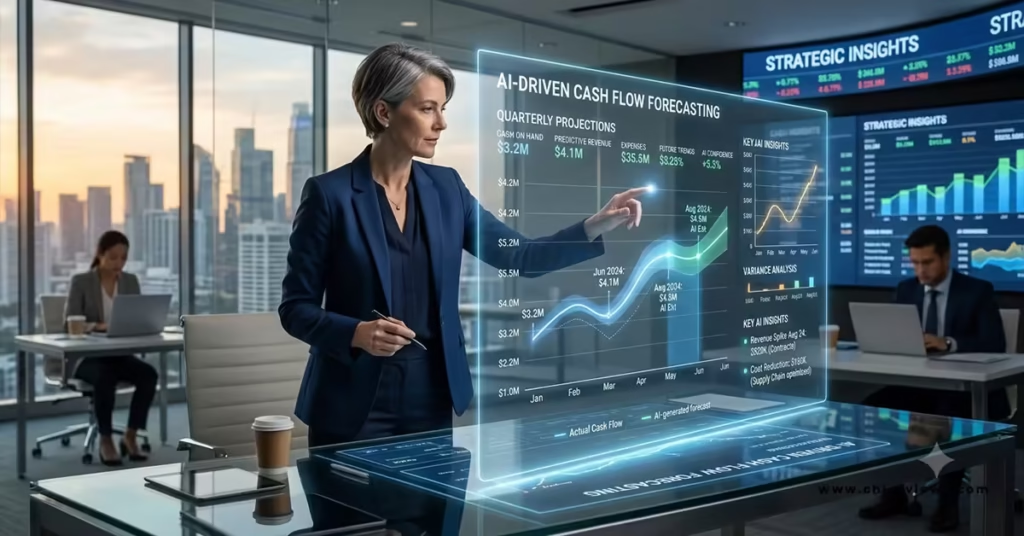
Machine-learning models ingest bank feeds, open AR and AP, historical payment patterns, and sometimes external credit or market data. They predict individual invoice settlement dates rather than broad category averages. Simulations then run multiple outcomes—delayed receipts, accelerated outflows, volume shifts—so you see a range of possible cash positions instead of a single optimistic number.
The practical difference shows up in three places. First, daily or intra-week reforecasting becomes routine instead of a fire drill. Second, collections teams get prioritized lists of accounts most likely to pay late. Third, treasury can test “what if we pull this payment forward or push that one back” without rebuilding the entire model.
One clean analogy: traditional forecasting is like driving with the rear-view mirror and occasional glances ahead. AI-driven cash flow forecasting for CFOs is the forward-facing radar that flags obstacles while you still have time to change lanes.
Where the accuracy gains come from—and where they don’t
Clean, granular data is non-negotiable. Models need at least 12–24 months of invoice-level history, consistent customer IDs, and reliable bank connectivity. When those inputs exist, published case results and vendor benchmarks show error rates dropping sharply versus pure historical averages. EY research has pointed to potential accuracy reaching 90% on 30-, 60-, and 90-day horizons with mature agentic approaches. Other 2026 analyses place well-implemented systems in the low-to-mid 90s for short-term forecasts.
But headline accuracy can mislead. The invoices that matter most are the late ones. A model that scores 90% overall yet misses every stretched payment still leaves you exposed. Smart teams evaluate performance specifically on the late-payer cohort and on the cash-floor weeks that determine whether you need to draw a line of credit.
This focus on usable intelligence rather than vanity metrics is exactly what separates high-performing finance functions under the wider CFO priorities for agility resilience and intelligence 2026.
| Forecasting Approach | Typical Horizon Strength | Data Requirements | Key Limitation | Best Fit |
|---|---|---|---|---|
| Manual / Spreadsheet | 4–8 weeks | Low | Slow to update, high human bias | Very small teams or one-off scenarios |
| Traditional ERP / TMS rules | 8–13 weeks | Medium | Static assumptions, weak late-payer prediction | Stable businesses with limited seasonality |
| AI-driven (ML + simulation) | Daily to 13+ weeks | High (clean AR/AP + bank feeds) | Requires data hygiene and model governance | Mid-market and enterprise needing agility |
| Agentic AI platforms | Multi-horizon with auto-reforecast | High + external signals | Higher implementation cost | Teams already running continuous planning |
Step-by-step action plan for beginners and intermediate teams
- Audit your current forecast error. Pull the last six months of 13-week forecasts versus actuals. Note the biggest misses and whether they came from late receipts, early payments, or volume surprises.
- Clean the input data first. Standardize customer and vendor IDs, fix open AR aging categories, and confirm daily bank feed reliability. Skip this and the model will simply amplify the noise.
- Choose one high-frequency process—usually the rolling 13-week direct cash forecast—as the pilot. Leave the longer-term indirect forecast in your existing planning tool for now.
- Select a platform or module that predicts at the invoice level and runs scenario simulations. Demand a clear explanation of how it scores late-payer risk.
- Set success metrics before go-live: reduction in forecast-to-actual variance on the critical cash-floor weeks, hours saved on manual updates, and earlier identification of at-risk receivables.
- Run the AI forecast in parallel with the old process for 6–8 weeks. Compare, calibrate, and only then cut over.
- Embed the output into weekly cash meetings. Make the model’s assumptions visible so the team learns to challenge and improve them.
What I’d do if I walked into a mid-market company tomorrow: start with the data audit and a focused 13-week pilot. Prove a measurable drop in surprise shortfalls within one quarter. Use that credibility to expand.
Common mistakes and how to fix them
Mistake one: buying the tool before fixing the data. Models trained on messy AR aging or incomplete bank history produce confident but wrong numbers. Fix—spend the first 4–6 weeks on data quality and process ownership.
Mistake two: judging success only by overall accuracy percentage. A model can look excellent on average and still miss the week that forces emergency borrowing. Fix—track performance specifically on late invoices and on the lowest projected cash points.
Mistake three: treating the forecast as a black box. When assumptions are hidden, finance teams stop trusting the output. Fix—require explainable drivers for every material prediction and keep a simple assumption log that the team reviews weekly.
Mistake four: stopping at the treasury view. The real leverage comes when sales, operations, and collections act on the same signals. Fix—share prioritized late-payer lists and scenario impacts with the people who can influence the outcome.
Key Takeaways
- AI-driven cash flow forecasting for CFOs replaces lagging historical averages with predictive, invoice-level signals that update continuously.
- Clean AR, AP, and bank data remain the foundation; without them even the best models underperform.
- Focus measurement on late-payer prediction and cash-floor accuracy rather than headline percentages.
- A focused 13-week pilot delivers the fastest proof of value and builds internal credibility.
- Scenario simulation turns the forecast from a report into a decision tool for capital and collections.
- This capability directly supports the intelligence pillar inside CFO priorities for agility resilience and intelligence 2026, giving leaders earlier visibility and tighter control.
- Governance and human review stay essential—AI surfaces the signal, people still own the action.
Finance teams that treat cash forecasting as a continuous intelligence system rather than a periodic report gain both breathing room and strategic speed. Start with the data audit, run one clean pilot, and measure the weeks that actually matter. That sequence turns AI from an experiment into an operating advantage.
FAQs
How accurate is AI-driven cash flow forecasting for CFOs in practice?
Well-implemented systems commonly reach the mid-to-high 80s or low 90s on short-term horizons when data quality is high. The more important metric is how reliably the model flags late payers and the lowest cash points, not the overall average.
Does AI-driven cash flow forecasting for CFOs replace the need for human judgment?
No. It surfaces patterns and scenarios faster. Finance leaders still set the cash floor, decide which risks to accept, and act on the recommendations. The best results come from human-plus-machine workflows.
Where does AI-driven cash flow forecasting fit inside broader CFO priorities for agility resilience and intelligence 2026?
It is a core intelligence capability. Better forecasts enable faster capital moves (agility) and earlier detection of liquidity pressure (resilience), making it one of the highest-ROI starting points for finance transformation.

